Investing in bricks and mortar in 2026: Costa del Sol vs Dubai vs Miami, a true comparison
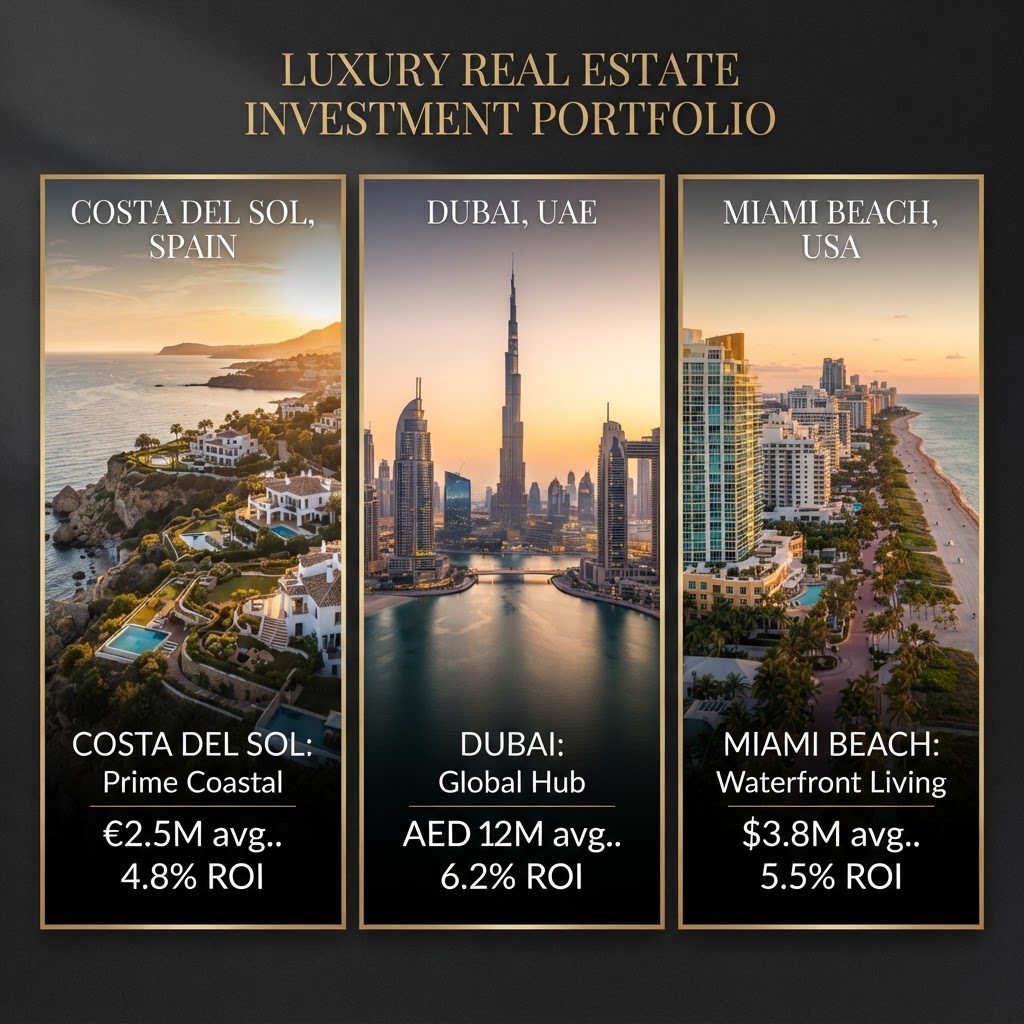
The Costa del Sol, Dubai, and Miami cater to different investor profiles: the Costa del Sol offers sustained capital appreciation and a European legal framework, Dubai offers high gross yields without local income tax but with a more volatile market, and Miami provides access to the dollar with significantly higher taxation and maintenance costs.
This article compares what is almost never compared: not the headline yield, but what remains after taxes, management, vacancies, and exit costs.
The comparison table
| Costa del Sol / Axarquía | Dubai | Miami | |
|---|---|---|---|
| Realistic entry ticket | €180,000 - €400,000 | €200,000 - €500,000 | $350,000 - $700,000 |
| Average gross yield | ~6.5 - 6.7% (Spain, 2026) | ~5.5% on average; 7.8% in studios | Variable by submarket |
| Recent year-on-year appreciation | +7.6% (Málaga prov., July 2026) | Mature cycle after strong expansion | Moderate |
| Rental income tax | Yes (IRPF / IRNR) | No local income tax | Yes (federal + local) |
| Annual property tax | IBI, low | Very low | High property tax |
| Legal certainty | EU framework, Land Registry | Solid registry, different framework | Solid, expensive litigation |
| Currency | Euro | AED (pegged to the dollar) | Dollar |
| Currency risk for a Spaniard | None | Yes (via dollar) | Yes |
| Exit liquidity | High on the coast | High in prime areas, low elsewhere | High |
| Recurring maintenance costs | Low-medium | Medium (service charge) | High (HOA + insurance) |
| Remote management cost | Low (same country) | Medium-high | High |
| Language and time zone barrier | None | Medium | Medium |
Costa del Sol and Axarquía: what you are really buying
The numbers. The province of Málaga closed July 2026 at €4,272/m², 7.6% more than the previous year. Málaga city reached an all-time high of €3,937/m². The average gross rental yield in Spain stood at 6.5-6.7% in 2026, a decrease compared to the 7.2-7.3% of the previous year — precisely because prices are rising faster than rents.
What you are really buying:
- European legal framework. Land Registry, public notary, security of title. In the event of a dispute, courts in your language and half an hour away by car.
- Structural, not speculative demand. Consolidated tourism, international residents, digital nomads, European retirees. It does not depend on a single driver.
- Operational proximity. You can visit the property, supervise work, and choose the tenant yourself. It sounds minor until you manage remotely.
- Liquid exit. At the right price, 4-8 weeks.
What you are not buying:
- Spectacular returns. The 6.5% gross becomes 4-5% net after IBI, community fees, insurance, vacancy, and maintenance.
- Cheap entry. On the beachfront of the Costa del Sol, the ticket is no longer an opportunity.
- Regulatory freedom in tourist rentals. This is the critical point and deserves its own paragraph.
Tourist rental: verify before buying. The Andalusian regulatory framework for tourist accommodation has changed significantly, with new requirements and the empowerment of local councils to adopt restrictive measures in certain areas. Furthermore, the statutes and agreements of the homeowners' association can condition the activity. Never buy a property valuing a tourist return that you have not verified can be maintained. It is the most expensive mistake I see in the region.
Dubai: profitability, risks, and the small print
The numbers, with an important nuance. Very disparate yields are published for Dubai, and the reason is methodological. Market data places the average gross yield around 5.5%, but with huge dispersion by typology: around 7.8% in studios and 3.8% in homes with four or more bedrooms.
When a salesperson shows you an 8%, they are almost always talking about gross returns on studios in specific developments. Always compare the same typology and the same basis of calculation.
In favour:
- No local tax on rental income or capital gains. This is the central argument, and it is real.
- Very low annual property taxes.
- High gross yields on small units.
- Professionalized market, with a wide range of full-service management.
- Currency pegged to the dollar, providing predictability against the local currency.
Against:
- A Spaniard who is a tax resident in Spain pays tax in Spain on their worldwide income. Just because Dubai does not levy tax does not mean you do not pay. It is the most costly confusion in the sector.
- Marked cycles. The market has seen strong expansions and strong corrections. It is not a "buy and forget" market.
- Very high volume of new construction, with pressure on rents in some submarkets.
- Annual service charges that can significantly erode net profitability and must be verified building by building.
- Very uneven liquidity. Excellent in consolidated areas, much worse outside them.
- Off-plan. Buying off-plan carries delivery and deadline risk. You must verify the developer and guarantees.
Miami: dollars, hurricanes, and the small print nobody reads
In favour:
- Dollar exposure as currency diversification.
- Deep and highly liquid market, with consolidated international demand.
- Solid legal certainty and a developed mortgage market.
- Structural Latin American demand, which sustains the high-end segment.
Against — and this is what breaks many business cases:
- High annual property tax. This is a substantial recurring cost that does not exist to that magnitude in Spain.
- Very expensive property insurance. Hurricane and flood risk. Premiums in Florida have risen sharply in recent years and remain a first-order factor.
- High HOA (community fees), especially in high-rise buildings. And after recent episodes, many communities have approved significant assessments for reserves and structural reinforcements.
- US taxation for non-residents, with withholding taxes on rents and specific regulations on sales.
- Higher transaction and management costs.
Miami's arithmetic is deceptive: an attractive gross yield can be reduced by half after property tax, insurance, and HOA. Never evaluate Miami on a gross basis.
The mistake that costs the most money: believing Dubai is tax-free for you
It deserves its own section because I see it constantly.
If you are a tax resident in Spain, you pay tax in Spain on your worldwide income. The returns from a property in Dubai or Miami form part of your taxable base in the Spanish IRPF (Personal Income Tax), regardless of whether the country of origin does not tax them.
What Dubai saves you is the local tax. Not the Spanish one.
To that, one must add, depending on the case:
- Possible obligation to declare assets and rights abroad when certain thresholds are exceeded.
- Consideration of the property in the Wealth Tax or equivalent figure, depending on the autonomous community and thresholds.
- Application, where applicable, of the relevant double taxation agreement.
None of these things make the investment bad. What makes the investment bad is calculating the profitability without them. Before buying abroad, a conversation with a Spanish tax advisor is not optional.
The 5 mistakes of the Spanish investor buying abroad
1. Comparing gross yields. Gross vs. gross means nothing when taxes, insurance, and community fees are radically different. The only honest comparison is net after taxes and all recurring costs.
2. Not calculating the exit cost. Transfer taxes, commissions, non-resident withholdings, repatriation of funds, and exchange rates. An investment is not closed until the money returns to your account.
3. Ignoring vacancies. Brochures calculate at 100% occupancy. Reality has empty months, turnover, and defaults. An 8% annual vacancy eats up more than it seems.
4. Buying without having set foot in the place. The floor plan does not show the real orientation, the noise, the quality of execution, or what is on the other side of the street. In Axarquía, this is obvious to anyone; 5,000 kilometres away, people forget it.
5. Trusting those who are paid to sell. A developer's salesperson is not an independent advisor. If no one on your side has an incentive to tell you not to buy, you don't have advice: you have a salesperson.
How a real estate personal shopper works
A real estate personal shopper represents the buyer, not the seller. It is a difference of incentive, not name.
What they provide in practice:
- Definition of the investment criteria before looking at a single property: target return, horizon, required liquidity, and risk tolerance.
- Active search, including offers that are not published.
- Technical and documentary verification: liens, real surface areas, licenses, real state of the construction, urban planning status.
- Independent valuation of whether the asking price is market value.
- Negotiation on behalf of the buyer, with technical information on the table.
- Coordination of notary, tax, and financing.
Which market fits which profile
Profile 1 · Patrimonial investor, long horizon, risk aversion. → Costa del Sol and Axarquía. Known legal framework, no currency risk, sustained appreciation, liquid exit, close management. Profitability is not the highest, but it is the most predictable.
Profile 2 · Investor seeking current income and accepting volatility. → Dubai, with three conditions: small units in consolidated areas, service charge verified before buying, and Spanish tax calculation done beforehand.
Profile 3 · Investor looking to diversify currency with a high ticket. → Miami, evaluating on a net basis and budgeting property tax, insurance, and HOA as structural costs, not as unforeseen expenses.
And a transversal recommendation: no investor should concentrate their real estate exposure in a single market if they have enough volume to diversify. But diversifying means knowing the three, not buying in the third because the brochure was pretty.
Frequently asked questions
Where is it most profitable to invest in 2026?
It depends on what is measured. In gross rental yield, Spain stood at around 6.5-6.7% in 2026 and Dubai at around 5.5% on average, with up to 7.8% in studios. In net profitability after taxes, the comparison changes depending on your tax residence. There is no universal winner: there is the market that fits your profile and your horizon.
What taxes does a Spanish resident pay when buying in Dubai?
In Dubai, practically none on rental income or capital gains. In Spain, all of them: as a Spanish tax resident, you pay tax on your worldwide income in your IRPF. Furthermore, information obligations regarding assets abroad and the consideration of the property in the Wealth Tax may apply. Consult with a Spanish tax advisor before buying.
Can I finance the purchase from Spain?
For properties in Spain, no problem. For Dubai and Miami, there are local financing products for non-residents, generally with a lower percentage of financing, higher rates, and more document requirements. Some investors choose to finance in Spain with a guarantee on a Spanish asset and buy cash abroad.
What is a real estate personal shopper and when is it worth it?
It is a professional who represents the buyer —not the seller— and is responsible for defining the investment criteria, searching, technically verifying, and negotiating. It is worth it when the ticket is high, when you buy remotely, or when you do not know the market well enough to detect what a brochure doesn't tell you.
Is it a good time to buy on the Costa del Sol with prices at highs?
Prices are at all-time highs and are rising by around 7.6% year-on-year in the province. This increases the entry cost and compresses rental profitability, which has fallen from 7.2% to 6.5% in a year. For long horizons with sustained structural demand, it remains a solid market; for those looking for a cheap entry, it is not the moment. The answer depends on your horizon, not the headline.
Are you considering investing inside or outside?
I work in the Costa del Sol and Axarquía as a real estate judicial expert and as a personal shopper, and I also operate in international markets. If you are considering an operation, I can perform the technical verification and tell you with data whether the price and promised profitability hold up.
📩 Request an investment strategy session
Notice: this article is for informational purposes and does not constitute investment or tax advice. Past performance does not guarantee future results. The taxation of real estate investments abroad depends on your tax residence and personal circumstances; consult with a tax advisor before investing.
Sources: idealista, Gross rental yield of housing for rent, first and second quarter of 2026 · idealista, Housing price report for sale — Málaga capital and province, July 2026 · Global Property Guide, Gross rental yields — United Arab Emirates, second quarter of 2026 · Andalusian regional regulations on dwellings for tourist use.
Are you interested in reading more? Cadastral reference value · How a property is valued · Selling in Andalusia: documentation, costs, and taxes